Why Bitcoin's Price Differs Between Exchanges: 18 Venues Checked Every Minute
Vultax read Bitcoin's order books on 18 exchanges every minute for 28 hours. Half stayed within a basis point, the highest and lowest ordinary venues sat a median 5.8 bps apart, and Upbit ran 1.31% above. In four weeks of readings no gap survived fees; here is what a gap has to clear.
Typical gap between the highest and lowest venue
0.05.8 bps
Median of 1,095 minute readings across 16 exchanges, 12–13 September 2026; about $45 on a bitcoin near $77,000
- Upbit above the other venues
- +0.001.31%
- Median of 985 readings, range 1.07% to 1.53%, with Upbit's won price converted to dollars at a live exchange rate
- Venues within 1 bp of the pack on 80% of readings
- 09 of 18
- Binance, Bitget, Bitrue, BTSE, Bybit, Gate, Kraken, OKX and WhiteBIT
- Readings where the gap paid after fees
- 00 of 3,767
- Vultax's live crypto pack, 6 September to 2 October 2026, five major venues, 10 bps taker fee per side; best reading −2.1 bps
The short answer
Bitcoin does not have one price. Every exchange runs its own order book, and the books are held together only by traders who move money between them. Vultax read the books of 18 exchanges every minute from 19:16 UTC on 12 September to 22:57 UTC on 13 September 2026. Most of the time the large venues sat within a basis point, a hundredth of a percent, of each other, and the gap between the highest and lowest of 16 ordinary venues had a median of 5.8 basis points: about $45 on a bitcoin near $77,000.
A few venues sit apart for reasons you can name. Upbit, a Korean exchange where Bitcoin trades against won, ran a median 1.31% above the others once its price was converted to dollars. HTX sat a median 2.9 basis points high. BitMEX's price in this set comes from a perpetual swap, not a spot market, and ran about 5 basis points low.
Whether a gap pays comes down to four deductions: fees on both legs, the depth behind each quote, the time it takes to move money between venues, and the age of the data that showed the gap. Vultax's live crypto pack prices the first of them every ten minutes on five major venues, buying at one venue's ask and selling at another's bid. Across 3,767 readings from 6 September to 2 October no gap survived a 10-basis-point taker fee on each side; the best came to −2.1 basis points.
What was measured
The readings come from Vultax's own market-data service, which keeps an order book for Bitcoin against USDT on each exchange it connects to. Every 60 seconds Vultax recorded each venue's midpoint, halfway between its best bid and best ask, along with its spread. A reading was used only when at least ten venues had refreshed their book in the previous 60 seconds; 1,095 of 1,594 readings qualified.
Each venue is compared with the median of the 16 ordinary venues. Upbit and BitMEX are shown against that median but kept out of it, because one is converted from another currency and the other is a derivative.
Most venues agree within a basis point
Nine of the 18 venues stayed within one basis point of the pack on at least 80% of readings: Binance, Bitget, Bitrue, BTSE, Bybit, Gate, Kraken, OKX and WhiteBIT. Coinbase and Poloniex were just as close on midpoint but carried the widest ordinary spreads, 1.7 and 4.1 basis points, so the price you could actually trade at was further away than the midpoint suggests.
| Venue | Median vs pack | Middle 80% of readings | Readings more than 5 bps away | Median bid–ask spread |
|---|---|---|---|---|
| BitMEX (perpetual swap) | −4.8 bps | −7.0 to −3.1 | 42.7% | 1.13 bps |
| CoinEx | −2.4 bps | −5.3 to −0.6 | 13.6% | 0.13 bps |
| KuCoin | −0.6 bps | −1.8 to 0.8 | 0.0% | 0.01 bps |
| Coinbase | −0.4 bps | −2.1 to 1.0 | 0.5% | 1.73 bps |
| Poloniex | −0.4 bps | −1.8 to 1.0 | 0.0% | 4.06 bps |
| Kraken | −0.1 bps | −0.8 to 0.6 | 0.2% | 0.01 bps |
| Binance | 0.0 bps | −0.5 to 0.6 | 0.0% | <0.01 bps |
| Bitget | 0.0 bps | −0.5 to 0.5 | 0.1% | <0.01 bps |
| Bitrue | 0.0 bps | −0.5 to 0.7 | 0.6% | <0.01 bps |
| Gate | 0.0 bps | −0.6 to 0.7 | 0.1% | 0.01 bps |
| WhiteBIT | +0.1 bps | −0.7 to 0.8 | 0.2% | <0.01 bps |
| BTSE | +0.1 bps | −0.4 to 0.7 | 0.1% | 0.13 bps |
| Gemini | +0.1 bps | −1.0 to 2.0 | 3.0% | <0.01 bps |
| OKX | +0.1 bps | −0.4 to 0.8 | 0.0% | 0.01 bps |
| Bybit | +0.1 bps | −0.4 to 0.7 | 0.1% | 0.01 bps |
| MEXC | +0.1 bps | −1.4 to 1.0 | 0.5% | <0.01 bps |
| HTX | +2.9 bps | −0.5 to 4.5 | 5.2% | <0.01 bps |
| Upbit (won, converted) | +131.2 bps | +114.9 to +142.5 | 100% | 1.43 bps |
Download table figures:CSVJSON with sources
The venues that sit apart
Each large offset has an ordinary explanation, and none of them is a price error.
- Upbit - Bitcoin on Upbit trades against Korean won. Converted at a live won–dollar rate, it ran between 1.07% and 1.53% above the pack, with a median of 1.31%. Cross-border gaps like this are long documented: in their study of 2017 and 2018, Makarov and Schoar found price gaps far larger across countries than within them and tied them to limits on moving capital. The premium measures a border, not Bitcoin.
- BitMEX - the book in this set is XBTUSDT, a perpetual swap, whose price is held near spot by periodic funding payments rather than by traders moving coins between spot books. A derivative a few basis points from spot is not comparable to a spot quote.
- HTX - a median premium of 2.9 basis points on Bitcoin that became a discount of about 6.5 basis points on Ether. A venue-specific offset, not a signal about the market.
- CoinEx - about 2.4 basis points low, and more than 5 basis points away on 13.6% of readings.
Ether is wider, and not in the same places
Ether's venues were further apart. Across 364 readings with ten fresh books, the gap between the highest and lowest ordinary venue had a median of 9.9 basis points, against 5.8 for Bitcoin. HTX, high on Bitcoin, was 6.5 basis points low on Ether, and BitMEX's Ether contract was 6.1 low. Ether books refreshed less often in this feed, which is why fewer readings qualified.
When the gap is widest
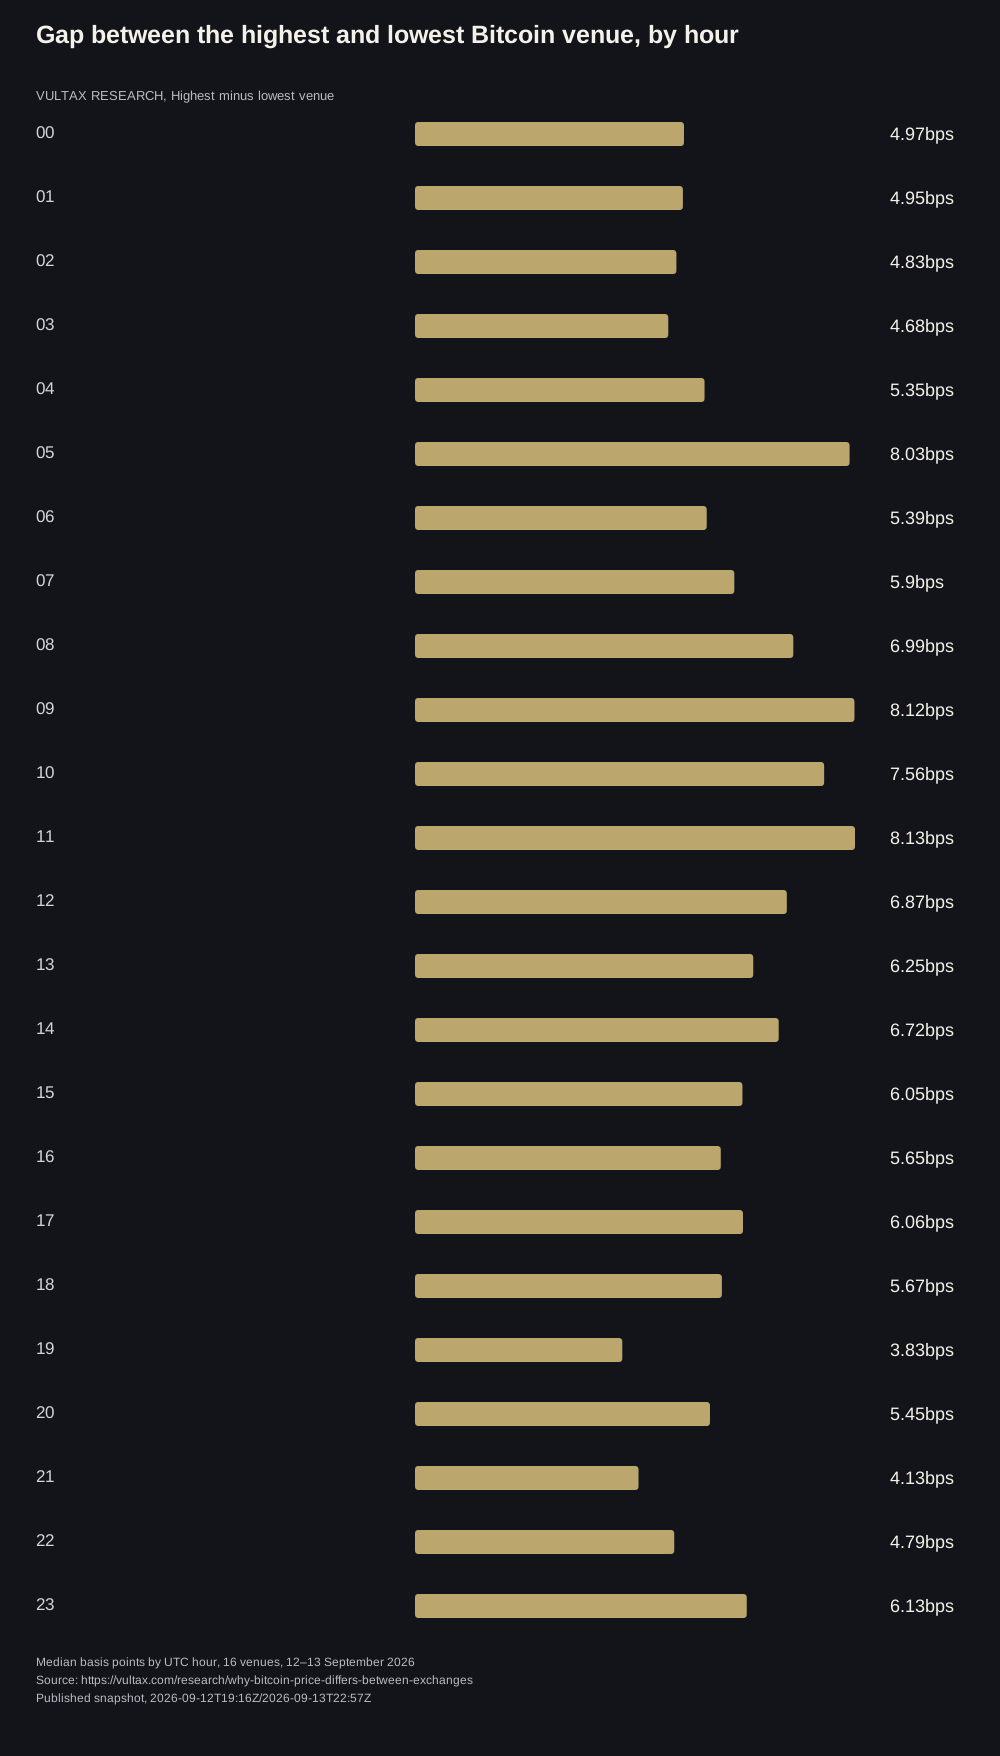
The gap between the highest and lowest venue was narrowest in the U.S. evening, about 4 basis points at 19:00 and 21:00 UTC, and widest in the Asian morning and European working day, about 8 basis points at 05:00 and between 09:00 and 11:00 UTC. With 28 hours of data each hour was observed once or twice, over a weekend, so read the shape rather than the exact values.
Gap between the highest and lowest Bitcoin venue, by hour
Median basis points by UTC hour, 16 venues, 12–13 September 2026
Chart: Vultax Research
Show the numbers
| Category | Highest minus lowest venue |
|---|---|
| 00 | 5.0 bps |
| 01 | 5.0 bps |
| 02 | 4.8 bps |
| 03 | 4.7 bps |
| 04 | 5.3 bps |
| 05 | 8.0 bps |
| 06 | 5.4 bps |
| 07 | 5.9 bps |
| 08 | 7.0 bps |
| 09 | 8.1 bps |
| 10 | 7.6 bps |
| 11 | 8.1 bps |
| 12 | 6.9 bps |
| 13 | 6.3 bps |
| 14 | 6.7 bps |
| 15 | 6.0 bps |
| 16 | 5.7 bps |
| 17 | 6.1 bps |
| 18 | 5.7 bps |
| 19 | 3.8 bps |
| 20 | 5.5 bps |
| 21 | 4.1 bps |
| 22 | 4.8 bps |
| 23 | 6.1 bps |
Download chart figures:CSVJSON with sourcesSVG chart
What a price gap has to clear
Before asking whether a gap pays, check four things, each of which can take the whole spread on its own: fees on both legs, the depth behind each quote, the time and capital needed to move money between venues, and how old the data behind the gap is. Then watch where gaps are widest: in this study about 8 basis points at 05:00 and between 09:00 and 11:00 UTC, and on venues that sit apart for structural reasons.
A gap is worth closing only if it is wider than the cost of closing it. Vultax's live crypto pack checks this every ten minutes across Coinbase, Kraken, OKX, Binance and Bybit: it buys at the cheapest venue's ask, sells at the dearest venue's bid, and charges an assumed 10-basis-point taker fee on each side. Across 3,767 readings from 6 September to 2 October, the gross gap between those five venues had a median of 3.8 basis points and never exceeded 17.9. After fees the result had a median of −16.3 basis points, and the best single reading, at 06:30 UTC on 17 September, was −2.1. None was positive. The first week alone, 1,029 readings to 13 September, gave a median gross gap of 3.3 basis points and a best reading of −7.0.
Deduction one: fees on both legs
A cross-exchange arbitrage is two trades, so it pays two taker fees. Published spot taker fees on major centralised venues commonly sit in the range of a few basis points to around ten, before volume tiers and token discounts, and the fee is charged whether or not the second leg fills at the price you assumed. The live pack's assumption of 10 basis points a side puts the round trip at 20 basis points, against a median gross gap of 3.3 across its five venues.
That is the ordinary case for the majors, not the exception: liquid markets are liquid because participants with lower fee tiers than yours have already competed the gap down to their cost floor rather than yours. Compute any gap net of your own fee tier before anything else.
Deduction two: depth, not price
A quote is a price for the next unit, not for your order. Wide gaps cluster on thin venues, and thin venues are thin at exactly the moment the gap appears: a 60-basis-point spread on a book that holds a few thousand dollars of depth at the touch is a spread on a trade too small to be worth the overhead, and it compresses as you walk the book. Even among the 18 venues here, Poloniex sat a median 0.4 basis points from the pack on midpoint but carried a 4.06-basis-point spread, so its tradable price was further away than its midpoint suggests.
Displayed size can also be withdrawn faster than an order can reach it, and reported volume says nothing about what a book will absorb.
- Compute the volume-weighted fill price across the levels your order would consume, on both legs
- Treat the spread as a function of size, not a scalar — it shrinks as size grows, and often crosses your fee floor before it crosses your target size
- Check whether depth at those levels has persisted, rather than sampling it once
Deduction three: inventory and transfer time
The textbook trade moves an asset from the cheap venue to the dear one. Moving coins or dollars between exchanges takes minutes at best, on-chain transfer plus crediting usually outlasts the gap, and withdrawal suspensions during volatile periods are common. Practitioners therefore pre-position inventory on both venues and rebalance separately.
That turns a timing problem into a capital problem. Returns must be judged against balances held across several exchanges, and the venue and custody risk they carry, not against the notional of one trade; a small edge per trade on capital that sits idle across venues is a very different proposition from the same edge on capital deployed once.
Deduction four: the age of your own data
A gap is at best as fresh as the older of the two quotes behind it. In Vultax's 16-venue feed latency study, median order-book snapshot latency at capture ran from 35.0 ms to 111.5 ms, but the 95th percentile ran from 288.5 ms to 589.7 ms and no venue held it under 100 ms. A cross-venue comparison inherits the worse tail of its two inputs, so it periodically sets a fresh price on one venue against a stale one on the other.
Stored snapshots age further. The books read for this 18-venue study were periodic snapshots: the median was 48 seconds old when read and one in ten was more than three minutes old, which is why readings with fewer than ten books under 60 seconds old were discarded. Some share of the gaps any scanner displays are artefacts of that skew rather than prices that existed at the same moment.
When gaps persist: the cross-border evidence
Makarov and Schoar's study of cryptocurrency market arbitrage, published in the Journal of Financial Economics, remains the most careful published account of when these gaps last. Deviations were much larger across countries than within them, and cross-country gaps could persist for days and weeks rather than seconds; during the period they studied, the average price ratio between the United States and South Korea reached roughly 40% at its extreme.
The gaps lasted not because traders failed to notice but because capital controls, banking access and the practical difficulty of moving fiat between jurisdictions kept arbitrage capital out. A gap that survives is usually one that something structural prevents anyone from taking, and that is what Upbit's median 1.31% premium on 12–13 September 2026 measures. Between venues where capital moves freely the deviations were far smaller and far shorter-lived, and that is the regime where fees and depth decide the outcome.
How to evaluate a scanner, including ours
Finding gross spreads is trivial, so the question to ask of any arbitrage tool is what it subtracts, and whether it says so. Vultax reports raw price-gap context across connected venues with the market-quality and liquidity-health context needed to judge whether real depth supports a gap. It does not represent gaps as executable profit, and it does not model your fee tier, your withdrawal limits, your inventory position or your own connectivity, all of which sit between a displayed gap and a filled trade.
- Does it show gross or fee-adjusted spreads, and does it say which?
- Does it show depth alongside price, or price alone?
- Does it publish its own feed latency distribution, including the tail?
- Does it distinguish a gap that persisted from one that appeared in a single snapshot?
- Does it claim executability, and on what basis?
What it means when you look up a price
Four practical points follow from the readings.
- A large venue's price is the market price - on Binance, Bybit, OKX, Kraken and the rest of the pack the midpoint was within about a basis point of the median almost all the time.
- Check what you are looking at - a perpetual swap, a won market converted to dollars, or a thin USDT book can each show a different number for honest reasons.
- An averaged price hides the differences - Vultax's spread research compares venues book by book, with spreads and depth, rather than blending them into one figure.
- Regional premiums are about moving money - Upbit's 1.31% says more about getting capital into Korea than about Bitcoin.
Context from elsewhere
The cross-venue question widened in 2026. Polymarket launched perpetual futures on 3 September with up to 20x leverage and no expiry, three months after Kalshi's bitcoin perpetuals went live. A perpetual on a prediction-market venue quotes the same asset as a spot book, so a scanner will show a gap; it carries every deduction above plus the funding payment that keeps a perpetual near spot, the same mechanism that holds BitMEX's swap a few basis points from the spot pack. The Polymarket product is barred to U.S. traders.
Venue risk is better documented too. In the October 2025 AWS outage Coinbase went dark while Binance, Kraken and OKX stayed up, and Coinbase's postmortem of its 7 May 2026 outage describes roughly eight hours down after an AWS thermal event and about twelve more to full recovery. A trade that needs both legs to fill is exposed to whichever venue fails first. Books have also thinned: Glassnode measured spot volume at its lowest since November 2023 in January 2026, and thinner books make quoted gaps look larger and executable size smaller at the same time.
Method and limits
Source: Vultax's market-data service, polled every 60 seconds for Bitcoin and Ether against USDT from 19:16 UTC on 12 September to 22:57 UTC on 13 September 2026. Each venue's book is a periodic snapshot; the median snapshot was 48 seconds old when read and one in ten was more than three minutes old, which is why readings with fewer than ten books under 60 seconds old were discarded. USDT is treated as equal to one dollar. Upbit is converted from won at the service's live exchange rate; BitMEX is its XBTUSDT perpetual swap.
The executable check comes from a separate Vultax measurement, the live crypto pack, which assumes a 10-basis-point taker fee per side on every venue; real fee tiers vary by venue and by trader. Feed latency figures come from a separate one-hour sample across 16 venues. Twenty-eight hours over a weekend is a short window, and hour-of-day figures and venue offsets can change. Nothing here is a recommendation to trade. Challenge a figure at [email protected]; material changes are logged in the changelog.
To watch the same venues live, the BTC venue desk in the Vultax terminal shows each connected exchange's book side by side, with the cross-exchange gap, depth and large trades.
Downloads contain the published study figures. Changing market widgets are separate. Use Vultax research with an AI assistant. Press note.
Questions this page answers
- Why is Bitcoin's price different on different exchanges?
- Each exchange has its own order book, kept in line only by traders moving money between venues. On 12–13 September 2026 most large venues sat within a basis point of each other; the widest pair of ordinary venues differed by a median 5.8 basis points.
- What is the kimchi premium?
- The extra price Bitcoin has tended to fetch on Korean exchanges. Measured on Upbit and converted from won at a live exchange rate, it was a median 1.31% over 12–13 September 2026. In the 2017–2018 period Makarov and Schoar studied, the average U.S.–Korea price ratio reached roughly 40% at its extreme.
- Is crypto arbitrage between exchanges profitable?
- Not on the gaps Vultax measured. Across 3,767 readings of five major venues from 6 September to 2 October 2026, no gap survived a 10-basis-point taker fee on each side, and the best came to −2.1 basis points, before transfer time and stale quotes. What remains is captured by market makers who hold inventory on both venues and pay lower fees than a taker.
- Why does a scanner show a spread that cannot be executed?
- Because it compares top-of-book prices, not the prices your order would receive. It leaves out taker fees on both legs, the depth behind each quote, the time and capital needed to move inventory between venues, and the age of the data behind each quote.
- Which exchange shows the real Bitcoin price?
- Any large spot venue is close: nine of 18 venues stayed within a basis point of the median on 80% of readings. Converted foreign-currency markets and perpetual swaps show different numbers for structural reasons.
Revision notes
This page is kept current. Each entry records what changed and when; the live figures above refresh on their own.
- The fee check now runs to 2 October: 3,767 readings since 6 September, none above the assumed fees. The widest gap was 17.9 basis points on 17 September, which left the best reading 2.1 basis points short.
- Now also covers what a price gap has to clear before it pays (fees on both legs, depth, transfer time and the age of the data) and the research on when cross-border gaps persist.
Sources and evidence
- Vultax live crypto pack
Cross-venue gap and executable check every ten minutes; 3,767 readings, 6 September to 2 October 2026
- Vultax methodology
How venue books are collected and normalised
- BitMEX — XBTUSDT instrument
Contract type of the BitMEX book in this study
- Makarov & Schoar — Trading and arbitrage in cryptocurrency markets (Journal of Financial Economics)
Cross-country price gaps and capital controls, 2017–2018
- Vultax: Crypto wash trading and real liquidity
Depth, spread and slippage as the measure of a venue, rather than reported volume
- Makarov & Schoar — Trading and Arbitrage in Cryptocurrency Markets (JFE 135:2)
Cross-country deviations persist for days and weeks; US/Korea price ratio reached ~40% at its extreme; within-country deviations far smaller
- Vultax — Crypto Exchange Feed Latency and Coverage: 16 Venues Measured
First-party latency measurement: 35.0–111.5 ms median, 288.5–589.7 ms p95 across 16 venues
- CoinAPI — Execution Quality in Crypto
Why effective spread and realised slippage, not quoted spread, determine execution cost
- Coinpaprika — Polymarket expands beyond prediction markets with 20x leverage perps (Sep 2026)
Perpetual futures launched 3 September 2026 with up to 20x leverage and no expiry, ten markets at launch and 67 within hours across crypto, equities, indices and commodities; U.S. traders barred. Kalshi's bitcoin perpetuals went live 3 June 2026.
- Coinbase — A postmortem of our May 7, 2026 outage
The venue's own account of the May 2026 outage traced to an AWS thermal event; roughly eight hours down and about twelve more to full recovery, by the postmortem's timeline.
- Yahoo Finance — AWS outage takes down Coinbase (20 Oct 2025)
Coinbase unreachable during an AWS outage while Binance, Kraken and OKX stayed online; 'all funds are safe'.
- Yahoo Finance — Bitcoin whales accelerate exchange activity in early 2026 amid fragile liquidity
CryptoQuant's exchange whale ratio (top-10 inflows over all inflows) at a ten-month high; Glassnode spot volume at its lowest since November 2023.
- CoinDesk — Crypto exchanges face a survival crisis as day traders disappear (28 Jul 2026)
A spot-volume slump that thins books before it shows in any headline volume figure; BitMEX announced a September shutdown.
Prices are order-book midpoints read from Vultax's market-data service over 28 hours and can differ from any single exchange's own display. The executable check uses an assumed fee. Nothing here is a recommendation to trade or financial advice.
Watch this measurement live in Vultax.
Bitcoin books from each connected exchange side by side, with the cross-exchange arbitrage view, venue depth and large trades.
New studies, by email.
Measured, sourced, and sent once per study. No digests, no promotions.
Continue reading
Crypto Exchange Feed Latency and Coverage: 16 Venues Measured
Order-book feed latency on 16 crypto exchanges: medians from 35.0 ms (Coinbase) to 111.5 ms (BTSE), a 95th percentile of 288–590 ms on every venue, and data in every minute of the day. Plus the coverage check that catches a feed that stays connected and stores almost nothing.
69% of Sharp Polymarket Price Moves Happened on Under $1,500
Vultax traced 1,985 sharp price moves in Polymarket's 400 busiest open markets over 14 days. In 1,375 of them less than $1,500 changed hands. 400 were one trader. Only 70 had many traders moving at once.
Polymarket's Up-or-Down Crypto Markets: 60% of Its Trades, Priced About Right, 1.6% Fee
Vultax counted 15.0 million Polymarket trades over 251 hours: 59.6% were up-or-down crypto bets, 379 wallets made most of them, and takers paid about 1.6% of notional on five-minute trades. In 2,497 markets checked against outcomes, Up won 50.2% and favourites won as often as priced.
115,006 Large-Trade Alerts: Where and When Crypto Whales Trade, by Venue and Hour
Every large-trade alert Vultax logged on six exchanges from 18 June to 3 September 2026: HTX carried 56% of large-trade notional, flow stayed close to balanced, 13:00–16:00 UTC held 23.6% of alerts, and weekends ran 23–30% quieter.